The Property Rights Nobody Talks About in Real Estate Tokenization
Real estate tokenization is often presented as a way to divide property into digital tokens, automate transactions, and make traditionally illiquid assets easier to access. But behind every tokenized property is a more fundamental question: What rights does the token actually represent?
A token does not automatically become a property deed simply because it exists on a blockchain. Depending on the legal structure, a token may represent equity in a property-holding entity, a debt claim, rental income rights, voting rights, or another contractual interest connected to the underlying asset.
This distinction is becoming increasingly important as real estate tokenization moves beyond experimentation toward more structured digital-asset infrastructure. Recent legal research continues to highlight the gap between blockchain-based representations and traditional property law, particularly around title, transfer, enforceability, and the rights attached to a token.
Real Estate Tokenization Is About More Than Ownership
The word “ownership” can make tokenized real estate sound straightforward. A property owner could theoretically divide a building into thousands of tokens, sell those tokens to investors, and record transfers on a blockchain. But the legal and economic relationship behind each token determines what the holder can actually do. In many structures, the physical property remains owned by an SPV, company, trust, or similar legal vehicle. The token then represents an interest in that structure rather than direct title to the property itself.
That creates several layers:
Physical asset → Legal entity → Contractual rights → Digital token
The blockchain manages the digital layer, while the underlying legal documents establish what those digital units mean. This is why successful real estate tokenization requires legal architecture and technology to work together rather than treating token issuance as a purely technical process.
1. The Right to Economic Value
One of the most important rights attached to a property token may not be ownership of the building at all. It may be a right to participate in its economic performance.
For example, a token could provide an economic interest connected to:
- Rental income
- Property sale proceeds
- Capital appreciation
- Refinancing proceeds
- Distributions from a property-owning entity
- Other contractual cash flows
This creates a distinction between owning the property and holding an economic claim associated with the property. A tokenization platform can use smart contracts to automate distribution calculations and transfer rules, but the underlying legal agreement still needs to define the holder's entitlement.
2. The Right to Receive Rental Income
Rental income is another property right that can be separated from direct control of the asset. Imagine a commercial property generating recurring rental payments. Instead of simply representing ownership, a token structure could be designed around a defined participation in the property's rental cash flow.
The workflow could look like:
Property → Tenants → Rental collections → Property manager/SPV → Distribution mechanism → Token holders
The blockchain can help automate the final stage by calculating and recording distributions according to predefined rules. However, the token holder's entitlement to those payments must originate from the legal and contractual structure. The blockchain does not independently create the underlying rental claim.
3. The Right to Vote
Property ownership can involve decision-making rights.
Should the property be refinanced?
Should a major renovation take place?
Should the asset be sold?
Should a new property manager be appointed?
In a tokenized structure, some of these decisions could potentially be connected to token-holder voting. But voting rights are not automatically created by token ownership.
The governing documents need to establish:
- Who can vote
- Which decisions require approval
- How voting power is calculated
- Whether different token classes have different rights
- What percentage is required for approval
- Whether certain decisions remain under management control
This creates an important distinction between economic rights and governance rights.
A token could provide an economic interest without giving the holder meaningful control over property decisions.
4. The Right to Transfer
Transferability is one of the major attractions of tokenized assets. A blockchain can record the movement of tokens almost instantly. But transferring a token and legally transferring an underlying property interest are not necessarily the same event. Academic research has highlighted this challenge: blockchain can represent intended property rights, while actual property ownership remains governed by applicable legal systems, registration requirements, and contractual arrangements. A tokenized real estate platform therefore may need rules covering:
- Eligible buyers
- KYC and AML requirements
- Investor restrictions
- Transfer approvals
- Holding periods
- Whitelisted wallets
- Secondary-market restrictions
- Jurisdictional limitations
The result is that programmable transferability does not necessarily mean unrestricted transferability.
5. The Right to Exit
Another property right that receives less attention is the right—or lack of a right—to exit.
Suppose a token holder wants to sell their position.
Who purchases it?
Can the token be traded on a secondary market?
Does the issuer provide redemption?
Is there a buyback mechanism?
Does the investor have to wait until the underlying property is sold?
These questions are particularly important because tokenization can make ownership units technically transferable without guaranteeing that a liquid market exists. A well-designed platform therefore needs to distinguish between technical transferability and actual market liquidity.
6. The Right to Information
Token holders may also require access to information about the underlying property and the entity managing it.
Depending on the structure, relevant information could include:
- Property valuation
- Rental collections
- Occupancy
- Operating expenses
- Debt obligations
- Insurance
- Major repairs
- Property management activity
- Financial statements
- Material changes affecting the asset
Blockchain can improve the transparency of transactions recorded on-chain, but information about the physical asset still has to come from trusted off-chain sources. This creates the broader oracle problem: the blockchain can verify what has been recorded on its network, but it cannot independently verify whether an external property valuation, rent payment, inspection report, or legal document is accurate.
7. The Right to Proceeds When the Property Is Sold
A property's eventual sale can create another layer of rights. Consider a tokenized commercial building that is eventually sold. The tokenization structure may specify that holders receive a defined share of the net proceeds after expenses, debt repayment, taxes, and other obligations. That means the token could represent a claim connected to a future capital event rather than direct control over the property.
The distribution waterfall becomes critical:
Sale price → Transaction costs → Debt obligations → Taxes/fees → Other liabilities → Eligible distributions → Token holders
The precise waterfall should be established before tokens are issued.
8. The Right to Collateral or Financing Value
Tokenized property interests may also become connected to financing arrangements. For example, a token representing an eligible economic interest could potentially be used within a structured lending arrangement, subject to applicable law, platform rules, and market infrastructure. This introduces another question:
Can the token holder pledge the token or the rights represented by it as collateral?
The answer depends on the legal nature of the token and the relevant agreements. The broader concept is significant because tokenization does not necessarily have to stop at ownership representation. Digital property interests could potentially become components of broader capital-market infrastructure.
9. The Right to Enforce the Underlying Claim
Perhaps the most overlooked issue is what happens when something goes wrong.
What happens if:
- Rental distributions stop?
- The property is damaged?
- The property manager defaults?
- Debt obligations become due?
- The issuer becomes insolvent?
- A token is transferred incorrectly?
- The underlying property is sold without expected distributions?
A token holder needs more than a blockchain transaction history.
They need to understand what legal claim they possess and how that claim can be enforced. Recent legal analysis of tokenized real estate emphasizes this disconnect between the technological ability to create a token and the legal authority required for that token to convey or represent enforceable real property rights.
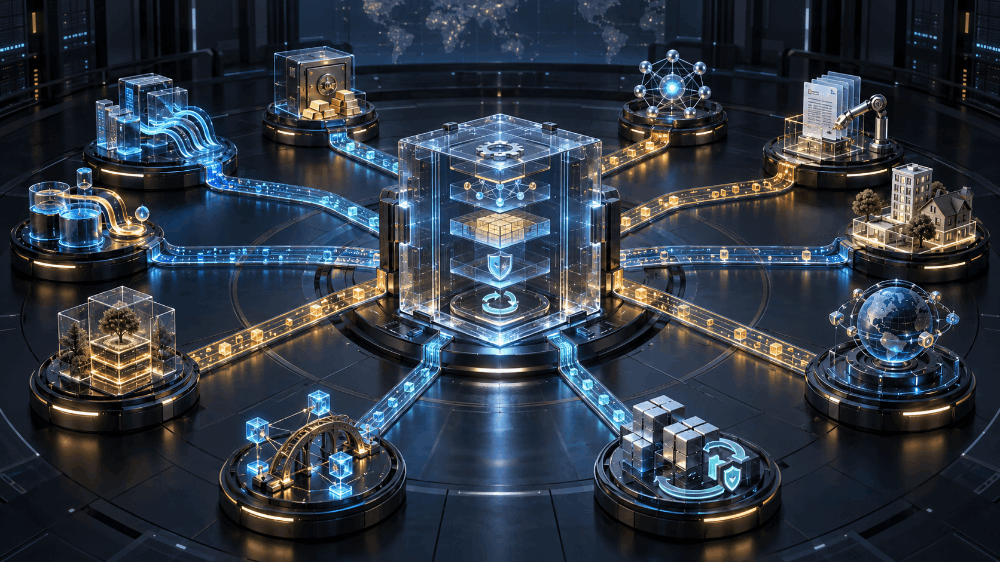
The Hidden Architecture Behind a Property Token
This leads to a more useful way of thinking about real estate tokenization.
The token itself is only one component.
A practical architecture may involve:
Property
↓
Legal ownership structure
↓
SPV / company / trust
↓
Operating and investor agreements
↓
Defined economic and governance rights
↓
Tokenization layer
↓
Smart contracts
↓
Investor wallets
↓
Distribution and transfer infrastructure
The blockchain becomes the digital coordination and settlement layer rather than a replacement for every existing component of property law.
This distinction is especially important because legal approaches differ across jurisdictions. Research published in 2026 continues to identify unresolved questions involving ownership, certification, fractional interests, rental rights, financing claims, and regulatory governance.
Why Property Rights Should Come Before Token Design
One common mistake in tokenization projects is beginning with the question:
“What type of token should we create?”
A stronger starting point is:
“What rights should the token represent?”
The answer can then determine the appropriate token model and technical architecture.
For example:
Intended RightPossible Digital RepresentationEconomic interestEquity/security-style tokenRental-income participationIncome-linked tokenDebt claimDebt tokenGovernance participationVoting-enabled tokenProperty-specific interestAsset-backed digital instrumentFund participationFund-interest tokenAccess/use rightsContractual utility or access token These are conceptual structures rather than universal legal classifications. The actual treatment depends on the asset, legal entity, contractual documentation, and applicable jurisdiction.
Smart Contracts Can Enforce Rules—But They Cannot Replace Legal Structure
Smart contracts are one of the most powerful components of tokenized real estate infrastructure.
They can potentially automate:
- Ownership records
- Transfer restrictions
- Distribution calculations
- Investor eligibility
- Voting mechanisms
- Payment schedules
- Compliance checks
- Redemption logic
But automation only works properly when the underlying rules are clearly defined.
A smart contract can execute:
“Distribute 5% of eligible rental proceeds to qualifying token holders.”
It cannot independently determine whether that 5% distribution is legally owed unless the underlying legal framework establishes the obligation. This is why some emerging real estate token standards explicitly connect digital tokens with legal agreements describing the rights attached to the property.
From Property Tokenization to Rights Tokenization
The future of real estate tokenization may therefore be less about simply putting buildings on blockchain and more about digitally structuring the rights surrounding those buildings. A single property could potentially support different digital instruments representing different layers of value:
Ownership rights
Income rights
Debt rights
Governance rights
Usage rights
Transfer rights
Exit rights
Collateral rights
The important development is not merely turning a property into a token. It is creating programmable infrastructure around the different economic and contractual relationships connected to that property.
What This Means for Real Estate Tokenization Platforms
For businesses developing a real estate tokenization platform, this changes the technology requirements.
A platform may need more than token minting.
It may need infrastructure for:
- Asset onboarding
- Legal-document management
- Investor verification
- KYC/AML workflows
- Token issuance
- Wallet management
- Permissioned transfers
- Ownership records
- Distribution management
- Voting
- Property reporting
- Cap-table management
- Secondary-market workflows
- Compliance monitoring
- Audit trails
The platform therefore becomes an orchestration layer connecting property data, legal rights, financial flows, investors, and blockchain infrastructure. This approach also supports more flexible tokenization models because the technology can be designed around the rights being represented rather than forcing every asset into the same token structure.
The Real Question Behind Real Estate Tokenization
Real estate tokenization is often described as a process of converting physical property into digital assets. A more precise description is the digital representation and management of legally defined rights connected to real-world property.
That difference matters.
A blockchain can provide a transparent and programmable record. Smart contracts can automate predefined processes. Digital tokens can make certain ownership or economic interests easier to administer and transfer. But the value of those tokens ultimately depends on the rights behind them.
As tokenized real estate infrastructure develops, the projects that matter may not simply be those that tokenize the largest number of properties. They may be the platforms capable of connecting legal rights, asset data, financial claims, investor permissions, and programmable settlement into one coherent system. The next phase of real estate tokenization is therefore not just about putting property on-chain.
Conclusion
The most important question in real estate tokenization may not be “How do we tokenize this property?”
It may be:
“Which property rights are we actually putting into digital form?”
A token is only one component of the broader structure. Behind it sits a network of legal ownership, economic interests, governance mechanisms, income rights, transfer conditions, financing arrangements, and property data. As real estate tokenization develops, platforms that connect these layers could play an increasingly important role in creating usable digital property markets. The future of tokenized real estate may therefore depend not simply on putting properties on-chain, but on making the rights behind those properties clearer, programmable, transferable, and digitally manageable.