Receivables Tokenization: Turning Future Cash Flows Into Digital Assets
Businesses often generate substantial value through invoices, subscriptions, purchase orders, contractual payments, and other receivables. Yet these future cash flows may remain locked behind payment cycles that can stretch for weeks or months. Receivables tokenization introduces a digital approach to representing these financial claims, potentially allowing businesses to structure, manage, and finance future cash flows through blockchain-based assets.
Rather than waiting for receivables to mature, businesses can explore ways to turn predictable payment obligations into digitally represented financial instruments. This creates new possibilities for working capital, investor participation, financial marketplaces, and automated settlement.
What Is Receivables Tokenization?
Receivables tokenization is the process of creating digital tokens that represent defined rights or interests connected to receivables.
A receivable could arise from:
- Unpaid business invoices
- Trade transactions
- Subscription contracts
- Purchase agreements
- Rental payments
- Royalties
- Service contracts
- Commercial payment obligations
The token itself does not necessarily represent the invoice directly. Its legal meaning depends on the structure of the transaction and the rights assigned to token holders. For example, a company holding $5 million in eligible invoices could create a structured financing arrangement in which digital tokens represent defined economic interests in the cash flows generated by those receivables.
Why Future Cash Flows Matter
Receivables are valuable because they represent expected future payments. However, waiting for those payments can create working-capital pressure. A business may have completed a transaction and recorded revenue while still waiting 30, 60, or 90 days to receive payment.
This creates a timing mismatch:
Business activity today → receivable created → payment received later
Receivables Tokenization can introduce another layer between these stages by creating digital infrastructure for representing and potentially financing those future cash flows.
How Receivables Tokenization Works
A typical model can involve several stages.
1. Identify Eligible Receivables
The business identifies receivables that meet predefined criteria.
These may be evaluated based on:
- Debtor quality
- Payment history
- Contract terms
- Maturity period
- Jurisdiction
- Documentation
- Credit risk
2. Establish the Legal Structure
The rights associated with the receivables need to be clearly defined. Depending on the model, receivables may be assigned to a special-purpose vehicle or another legal structure before digital interests are issued.
3. Create Digital Tokens
A blockchain-based system can represent defined economic interests in the receivables. The token structure may specify ownership rights, payment rights, transfer restrictions, or other contractual conditions.
4. Onboard Eligible Participants
Investors or financing participants can be onboarded through identity verification and compliance procedures.
5. Manage Cash Flows
When debtors make payments, the corresponding funds can be distributed according to the legal and financial structure governing the tokenized receivables.
6. Maintain Records
Blockchain infrastructure can provide a digital record of token ownership, transfers, and relevant transaction activity.
Turning Invoices Into Financing Opportunities
One of the most important applications is invoice financing. Consider a company with $2 million in invoices that will be paid over the next 90 days. Instead of waiting for the entire amount to mature, the business could potentially structure those receivables into a financing product.
Eligible investors could provide capital against the underlying cash flows, while the business receives working capital earlier.
This does not eliminate credit risk. The quality of the underlying receivables, debtor payment behavior, legal enforceability, and transaction structure remain important.
Sure — here is the expanded version with about 50 additional words while keeping the same structure and SEO-friendly tone:
Benefits for Businesses
Improved Working Capital
Receivables tokenization can help businesses unlock liquidity from outstanding invoices before their payment due dates. This may provide earlier access to capital for operational expenses, supplier payments, expansion, and other business requirements. It can also help companies manage cash-flow gaps without waiting for the full receivable cycle to complete.
Transparent Digital Recordkeeping
Blockchain-based infrastructure can maintain a transparent and traceable record of token ownership, transfers, and transaction activity. This can improve visibility across the receivables lifecycle while reducing reliance on fragmented recordkeeping systems. Businesses may also benefit from easier reconciliation and improved access to transaction records.
Fractional Participation
Tokenized receivables can be structured into smaller digital units, potentially enabling multiple eligible participants to gain exposure to portions of an underlying receivable pool. This can create more flexible participation models for structured finance arrangements and support the creation of digitally managed financing structures.
Automated Processes
Smart contracts can automate predefined processes such as transfer rules, participant eligibility, payment calculations, and distributions. Automation may reduce manual intervention and help streamline certain stages of receivables management. This can potentially improve operational efficiency while creating more consistent execution of predefined transaction conditions.
Portfolio Diversification
Receivables-backed digital assets can provide eligible investors with exposure to cash-flow-based assets that differ from conventional equity, debt, or property investments. This may support the development of more diversified digital asset portfolios while creating additional structures for accessing business-generated cash flows.
Beyond Traditional Invoice Financing
Receivables tokenization can extend beyond conventional invoices, creating opportunities to represent different types of contractual or recurring cash flows through digital financial structures. This broader approach may allow businesses to explore alternative financing models based on predictable future receivables.
Subscription Receivables
Businesses with recurring subscription payments may be able to structure future revenue streams into financing arrangements. This could be relevant for software providers, digital platforms, media companies, and other subscription-based businesses with predictable customer payment cycles.
Trade Receivables
Importers, exporters, manufacturers, wholesalers, and distributors can generate receivables through commercial transactions that may become candidates for structured financing. Tokenization could provide a digital framework for representing these obligations while improving visibility into underlying receivable positions.
Rental Receivables
Property-related rental payments can potentially be represented through digital financial structures. Commercial landlords, property operators, and other businesses with recurring rental income may explore tokenized models for organizing and financing future cash flows.
Royalty Receivables
Companies receiving predictable royalty payments could potentially use future contractual cash flows as part of a financing model. This may apply to businesses generating income from intellectual property, licensing agreements, media rights, technology, or other contractual royalty arrangements.
Marketplace Receivables
Digital marketplaces may generate predictable payment obligations between buyers, sellers, and platform operators. Tokenization could help represent these receivables within structured digital frameworks, potentially supporting more transparent tracking, automated processing, and alternative approaches to working-capital management.
The Role of Smart Contracts
Smart contracts can provide programmable infrastructure for tokenized receivables.
Depending on the transaction design, smart contracts can support:
- Token issuance
- Transfer restrictions
- Investor eligibility rules
- Payment calculations
- Distribution schedules
- Ownership records
- Automated settlement workflows
For example, a receivables token could be configured with predefined rules governing how eligible cash flows are distributed. However, automation does not replace the underlying legal agreements. The enforceability of the receivable and the rights of each participant must remain clearly established outside the blockchain system where necessary.
Building a Receivables Tokenization Platform
A dedicated platform can bring multiple components together.
Asset Management Layer
Businesses can upload, categorize, and monitor eligible receivables.
Tokenization Engine
This layer manages token creation, issuance parameters, supply, and ownership records.
Investor Management
Investors can complete onboarding, review available opportunities, track holdings, and monitor distributions.
Compliance Infrastructure
KYC, AML, accreditation or eligibility checks, transfer restrictions, and transaction monitoring can be incorporated into the platform.
Payment Infrastructure
The platform can connect payment systems with tokenized assets to support collection and distribution workflows.
Reporting and Analytics
Businesses and investors can monitor outstanding receivables, maturity dates, payment activity, portfolio performance, and other relevant metrics.
A New Layer for Trade Finance
Receivables tokenization can also intersect with trade finance. Businesses involved in international commerce frequently deal with delayed payments, complex documentation, and multiple intermediaries. Digital representations of receivables could potentially improve the coordination of information and financing around these transactions.
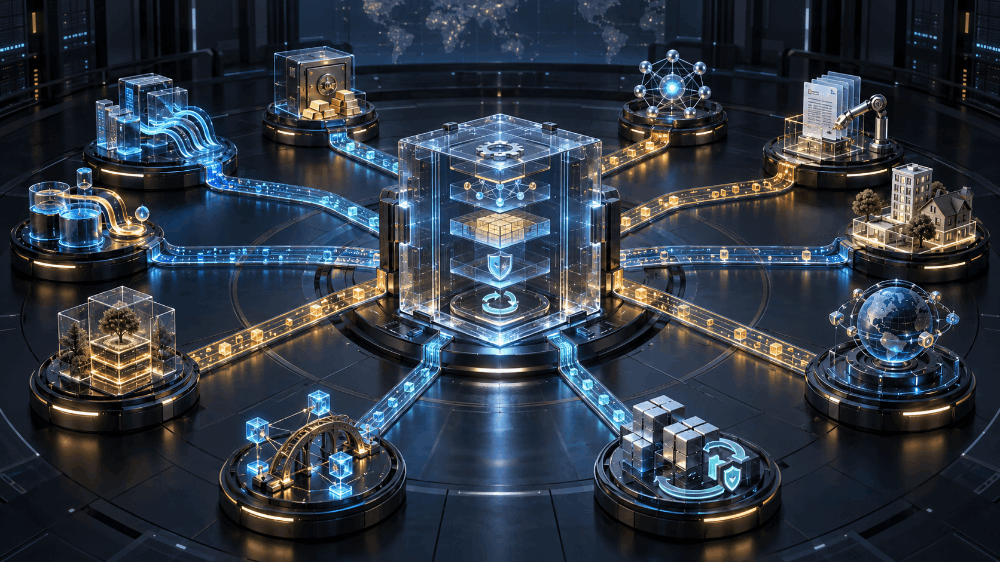
A tokenized trade receivable ecosystem could connect:
Seller → Receivable → Digital representation → Financing participant → Payment → Settlement
The actual implementation depends on legal ownership, financial regulations, payment infrastructure, and the participants involved.
Secondary Markets and Liquidity
One frequently discussed possibility is secondary-market trading. If tokenized receivables are legally transferable and an appropriate marketplace exists, investors may potentially be able to transfer their interests before the underlying receivables mature.
However, tokenization alone does not guarantee liquidity.
A functioning secondary market requires:
- Eligible buyers and sellers
- Regulatory compliance
- Transferable legal rights
- Reliable asset information
- Market infrastructure
- Appropriate pricing mechanisms
- Sufficient demand
Therefore, liquidity should be treated as a market outcome rather than an automatic feature of tokenization.
Risk Management Becomes Critical
Receivables are ultimately connected to payment obligations.
This makes risk assessment central to the model.
Platforms may need to evaluate:
- Debtor creditworthiness
- Concentration risk
- Payment history
- Invoice authenticity
- Duplicate financing
- Fraud exposure
- Default risk
- Legal enforceability
- Geographic exposure
- Currency risk
Technology can improve monitoring, but it cannot remove the economic risks associated with the underlying receivables.
Regulatory and Legal Considerations
Receivables tokenization can involve multiple areas of regulation depending on the structure and jurisdiction.
Businesses may need to consider:
- Securities regulations
- Assignment of receivables
- Contract law
- KYC and AML requirements
- Investor eligibility
- Data privacy
- Tax treatment
- Custody
- Payment regulations
- Cross-border restrictions
The legal classification of the token is particularly important because it determines the obligations that may apply to the issuer, platform, and investors.
Business Models Around Receivables Tokenization
The emergence of tokenized receivables can create opportunities for specialized businesses.
Potential models include:
Receivables Tokenization Platforms
Infrastructure for creating and managing digital representations of receivable interests.
Invoice Financing Marketplaces
Platforms connecting eligible businesses with financing participants.
Trade Finance Platforms
Digital infrastructure focused on commercial receivables and cross-border transactions.
Tokenized Credit Funds
Investment structures built around diversified pools of receivables.
Receivables Management Platforms
Systems for monitoring invoices, payments, maturities, and investor interests.
Compliance Infrastructure
Technology supporting identity verification, eligibility checks, transaction monitoring, and reporting.
Secondary Trading Platforms
Market infrastructure designed for permitted transfers of tokenized receivable interests.
These models demonstrate that the opportunity extends beyond token issuance itself.
What Businesses Should Consider Before Launching
A receivables tokenization project should begin with the underlying financial structure.
Businesses should determine:
- What receivables are being tokenized?
- Who legally owns the receivables?
- What rights does each token represent?
- Who is responsible for collecting payments?
- Which investors are eligible to participate?
- How will defaults and disputes be handled?
- How will investors receive distributions?
- Can the tokens legally be transferred?
- What compliance requirements apply?
- How will asset and investor data be managed?
Answering these questions before selecting technology can help create a more coherent tokenization model.
The Future of Cash-Flow Tokenization
The broader opportunity extends beyond invoices. As digital-asset infrastructure develops, businesses may increasingly explore tokenized representations of different forms of contractual cash flow.
Potential categories include:
- Trade receivables
- Rental income
- Subscription revenue
- Royalties
- Private credit
- Commercial contracts
- Equipment leases
- Consumer receivables
- Structured debt
This could contribute to a broader financial infrastructure where future cash flows become easier to represent, monitor, finance, and potentially transfer.
Conclusion
Receivables represent an important form of business value, but their delayed payment cycles can create working-capital challenges. Receivables tokenization offers a way to introduce blockchain-based infrastructure around these future cash flows, creating new possibilities for financing, investor participation, recordkeeping, and automated financial processes.
The opportunity is not simply about putting invoices on a blockchain. The larger transformation involves connecting legal rights, credit assessment, investor infrastructure, payment systems, compliance, and digital ownership into a coordinated financial ecosystem.
As businesses continue exploring tokenized real-world assets, receivables could become an important category where future cash flows are transformed into digitally structured financial opportunities.