Why Legal Structure Matters When Tokenizing Investment Funds

Investment fund tokenization is changing how certain financial interests can be represented and managed using blockchain technology. By converting eligible fund interests into digital tokens, fund managers can create new ways to record ownership, manage transfers, and interact with investors.
However, tokenization is not simply a process of creating a digital asset and placing it on a blockchain. Before a token is issued, there needs to be a clear understanding of what that token represents from a legal and operational perspective.
If the legal structure of an investment fund does not align with its token architecture, problems can emerge around ownership, investor rights, transfers, compliance, and recordkeeping. For this reason, legal structure should be one of the first considerations in any fund tokenization platform development project.
What Does Legal Structure Mean in an Investment Fund?
The legal structure defines how a fund is established, managed, and owned. It can determine how investors participate in the fund, what rights they receive, and how their interests can be transferred or redeemed.
Depending on the fund and jurisdiction, investors may hold shares, units, partnership interests, or other forms of participation.
These distinctions matter when a fund is tokenized.
A digital token should correspond to a clearly defined underlying interest. Investors should be able to understand what ownership of the token represents and how that ownership relates to the legal documentation governing the fund.
Without this foundation, blockchain records may show token balances without providing a clear framework for the rights associated with those balances.
Why Legal Ownership Must Match the Token
One of the central questions in fund tokenization is simple:
What exactly does one token represent?
It could represent an interest in a fund, a share of an entity, an economic entitlement, or another legally defined right. The answer affects how the token should be designed and managed.
For example, if a token represents a fund interest, the legal documentation should establish the relationship between the token holder and the underlying fund.
This becomes particularly important when tokens are transferred between investors. A blockchain transaction can record the movement of a token from one wallet to another, but the transfer process may still need to comply with restrictions associated with the underlying investment.
The technical transaction and the legal transaction therefore need to be considered together.
Token Rights Need to Be Clearly Defined
Tokenization can introduce different categories of rights depending on how the investment is structured.
These may include:
- Economic rights
- Distribution rights
- Voting rights
- Redemption rights
- Transfer rights
- Information rights
- Rights associated with different investor classes
If these rights are not clearly defined, investors may have difficulty understanding what their digital holdings actually provide.
The token design should therefore reflect the intended economic and governance structure of the fund. Legal documentation and technical implementation should communicate the same ownership model.
Investor Eligibility and Transfer Restrictions
Investment funds may have restrictions regarding who can invest and under what circumstances.
Depending on the structure and applicable rules, a fund may need to consider investor identity, jurisdiction, eligibility requirements, KYC and AML procedures, and restrictions on transfers.
This means a tokenized fund cannot necessarily operate like an unrestricted cryptocurrency.
For example, a fund may need to prevent transfers to wallets that have not completed required verification. In such cases, the token infrastructure may need appropriate permissioning or whitelisting mechanisms.
These requirements should be considered before the smart contract is deployed.
How Legal Structure Affects Smart Contract Design
Smart contracts provide the technical rules governing blockchain-based assets, but they should not independently determine the legal rights of investors.
Instead, the legal and operational requirements of the fund should guide the technical architecture.
Depending on the fund model, smart-contract functionality may need to support:
- Approved investor wallets
- Restricted token transfers
- Minting and burning
- Role-based permissions
- Distribution mechanisms
- Redemption processes
- Different investor classes
- Administrative controls
For example, if fund interests can only be transferred between eligible investors, the smart contract may need to enforce appropriate transfer restrictions.
The goal is not simply to make the token function technically. The goal is to make the technology support the intended fund structure.
What Happens When Legal and Technical Structures Do Not Align?
Poor alignment between legal documentation and blockchain infrastructure can create several problems.
Ownership confusion
Investors may hold tokens without clearly understanding what rights those tokens provide.
Transfer problems
A token may technically be transferable even though the underlying fund interest is subject to restrictions.
Compliance gaps
Investor eligibility and transaction requirements may not be properly reflected in the digital infrastructure.
Recordkeeping issues
On-chain token balances may become difficult to reconcile with fund-administration records.
Investor disputes
Unclear rules around distributions, voting, redemption, or ownership can create uncertainty for investors and fund managers.
These issues demonstrate why legal planning should happen before token issuance rather than after the technology has already been deployed.
Jurisdiction Can Change the Tokenization Model
There is no universal legal structure for every tokenized investment fund.
The appropriate model can depend on the fund type, target investors, asset class, and jurisdictions involved.
Cross-border investment can introduce additional considerations because investor requirements and financial regulations can differ between jurisdictions.
For this reason, businesses planning a tokenized fund should obtain appropriate legal and regulatory advice for the jurisdictions in which the fund and its investors operate.
Technology teams can build the infrastructure, but legal professionals need to establish how the underlying investment should be structured and what rights investors should receive.
Legal Documents and Blockchain Infrastructure Must Work Together
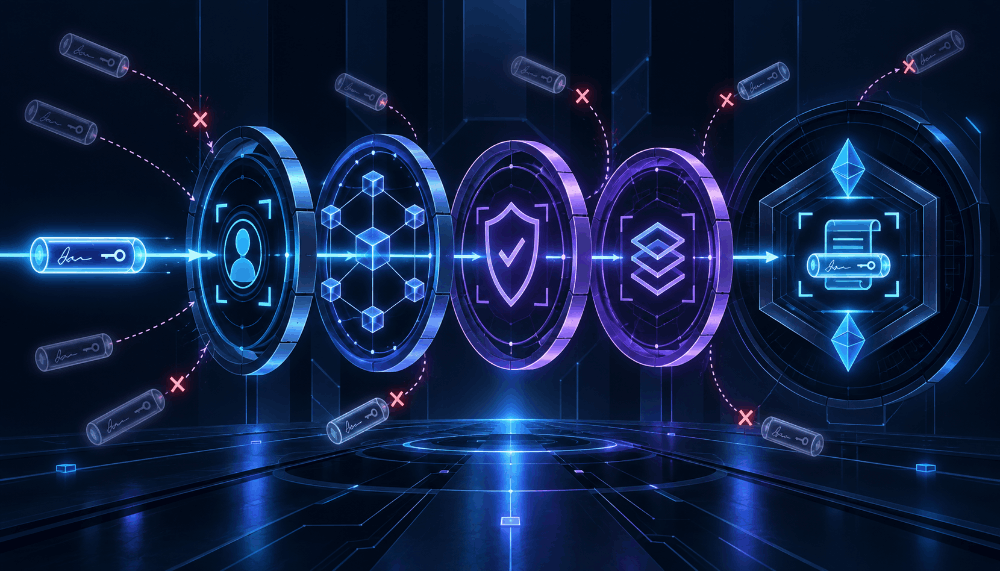
A successful tokenized fund requires coordination between its legal and technology layers.
The legal layer may include:
- Fund formation documents
- Subscription agreements
- Investor rights
- Transfer restrictions
- Governance rules
- Distribution terms
The technology layer may include:
- Token contracts
- Blockchain infrastructure
- Investor wallets
- KYC/AML integrations
- Transfer controls
- Investor dashboards
- Fund-management integrations
These layers should not be developed independently.
For example, if the legal documents establish transfer restrictions but the token contract allows unrestricted transfers, the system can create operational problems.
Likewise, if investor rights change but the token architecture cannot represent those changes, maintaining accurate records can become more difficult.
A Practical Framework for Structuring a Tokenized Fund
A structured approach can help reduce these issues.
1. Define the underlying fund interest
Determine exactly what the token will represent and what asset or legal interest sits behind it.
2. Establish the ownership model
Define who owns the underlying interest and what rights investors receive.
3. Identify investor requirements
Determine eligibility, onboarding, KYC, AML, and jurisdictional requirements.
4. Define token rights
Map economic, voting, distribution, redemption, and transfer rights to the digital asset.
5. Translate requirements into technology
Design the smart contracts, permissioning, wallets, and transfer mechanisms around the established rules.
6. Connect fund administration
Ensure blockchain records can work with NAV, investor records, reporting, and other fund-management systems.
7. Test the complete structure
Test the legal workflows, smart contracts, investor onboarding, transfers, and administrative processes before launch.
Building the Right Fund Tokenization Infrastructure
Once the legal framework and operational requirements are established, the technology needs to support the entire fund lifecycle.
Businesses evaluating fund tokenization services should consider more than token creation. The broader infrastructure can include smart-contract development, investor onboarding, KYC/AML integration, wallet management, transfer controls, investor dashboards, and fund-administration integrations.
This approach helps ensure that the blockchain layer supports the actual requirements of the investment fund instead of operating as an isolated technology component.
Common Mistakes to Avoid
Several mistakes can make fund tokenization unnecessarily complicated:
- Creating the token before defining the underlying legal rights
- Treating a fund token like an unrestricted cryptocurrency
- Ignoring investor eligibility requirements
- Designing smart contracts without considering legal restrictions
- Keeping blockchain records separate from fund-administration systems
- Assuming tokenization automatically creates market liquidity
- Applying the same structure across different jurisdictions
- Launching without sufficient technical and operational testing
Avoiding these issues requires coordination between legal, financial, compliance, and technology teams from the beginning.
Conclusion
Legal structure is one of the foundations of investment fund tokenization. A blockchain network can record ownership and automate certain processes, but it does not independently determine what investors legally own or what rights they receive.
The token, legal documents, investor onboarding process, compliance framework, and fund-management infrastructure should therefore be designed as connected parts of the same system.
Before issuing a tokenized investment fund, businesses should clearly define what the token represents, who can own it, what rights it provides, how transfers work, and how those rights will be managed over time.
Successful fund tokenization starts with understanding the fund and its legal structure not simply creating the token.